The short answer
A home inspection is your chance to understand the property before the contract deadline. It is not a guarantee that every future problem will surface, and it is not the same as the lender’s appraisal.
- Hire a licensed Florida home inspector and confirm their current status and experience with your property type.
- Schedule immediately. Leave room for follow-up evaluations inside the inspection period.
- Expect a long report. Length is normal — sort findings by seriousness, not by count.
- In South Florida, watch roof age, moisture, electrical, and impact protection. They affect insurance as well as safety.
- A four-point and a wind-mitigation report are for insurance. They do not replace a full inspection.
The full picture
A productive inspection helps you identify material concerns, expected maintenance, and the questions that need a different specialist. Your signed contract controls the inspection period and your options, so schedule the work promptly and review any contract or legal question with the appropriate real estate and legal professionals.
Choose a properly licensed inspector
Florida licenses individual home inspectors. The Florida Department of Business and Professional Regulation explains the home-inspector license and provides access to licensing information.
Before you book, confirm:
- Current license status
- Experience with your property type
- Scope of work and what is excluded
- Insurance
- Report format and turnaround
- Availability for questions after the inspection
A general inspection will not cover every system. Depending on the property, you may want separate evaluations for the roof, pool, seawall or dock, mold, termites and other wood-destroying organisms, septic system, well, elevator, generator, solar equipment, or specialized mechanical systems.
Understand the general scope
A typical inspection reviews the visible and accessible components of the structure, roof, exterior, interior, electrical system, plumbing, heating and cooling, and site conditions affecting the structure. Limitations should be stated in both the agreement and the report.
Furniture, stored items, finished surfaces, locked spaces, weather, utilities, and safety restrictions all limit what can be observed. Ask your inspector to identify what was not inspected, and whether access or another evaluation is recommended.
Pay attention to South Florida conditions
Property-specific concerns here usually include:
- Roof — age, covering, flashing, drainage, prior repairs, visible storm damage
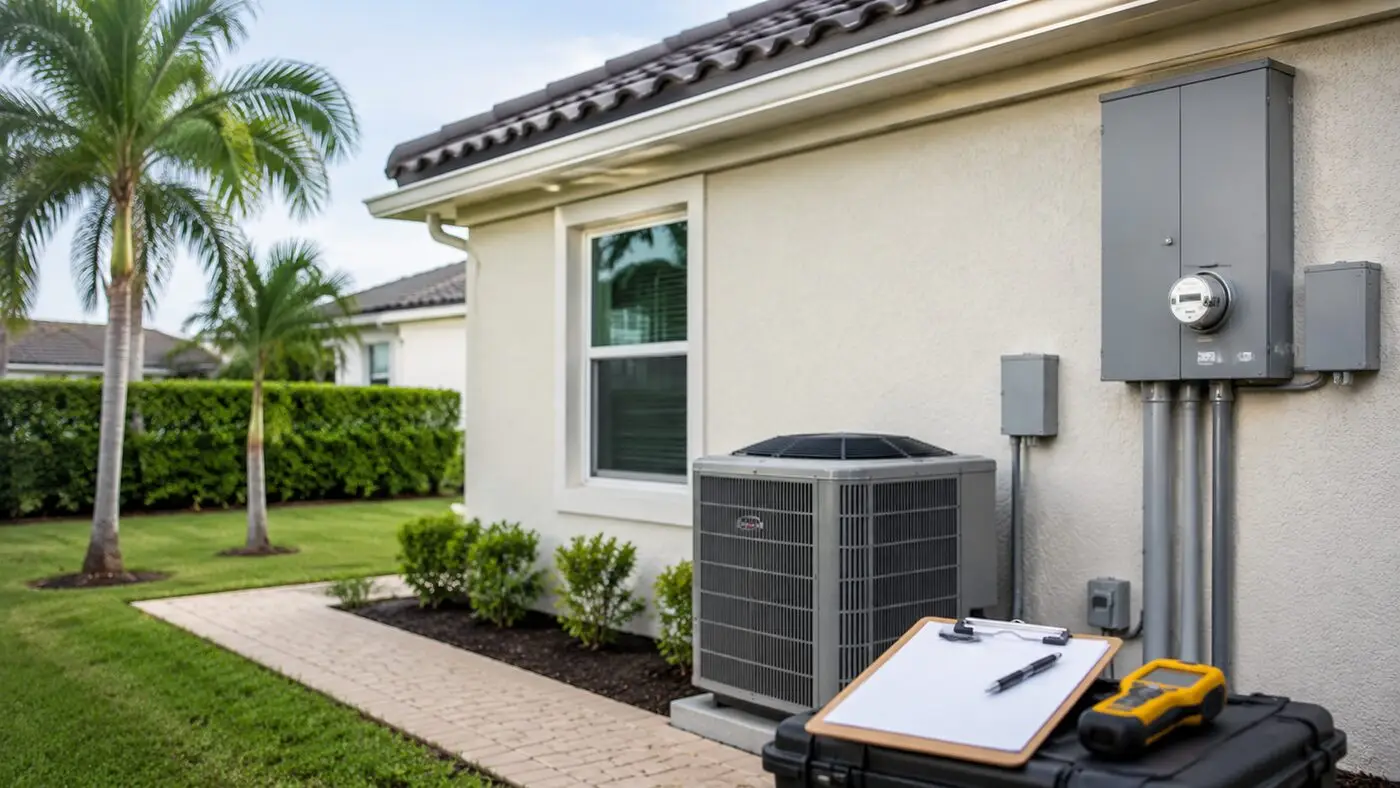
- Air conditioning — operation, condensate drainage, duct condition, signs of moisture
- Electrical — panels, wiring, protection devices, visible safety concerns
- Plumbing — supply and drain lines, water heater, fixtures, leaks, evidence of prior work
- Openings — windows, exterior doors, shutters, impact protection, and documentation
- Water — intrusion, drainage, grading, staining, conditions favorable to mold
- Site improvements — pool equipment, screen enclosures, docks, seawalls
Moisture deserves careful follow-up. The U.S. Environmental Protection Agency explains that controlling moisture is central to controlling mold. A general inspector may identify visible evidence or conditions of concern; sampling, remediation design, and health advice all require the appropriate specialist.
Know what the insurance reports are for
A wind-mitigation inspection and a four-point inspection may be required for your insurance application, depending on the carrier and property. They serve the insurer, and they are not substitutes for a full home inspection.
Ask your insurance professional which reports are needed, who may complete them, how current they must be, and what documentation supports available features.
Get insurance guidance during the contract period, not at closing. Roof age, electrical, plumbing, HVAC, prior claims, flood zone, and association coverage can all affect what options are available to you — and that is much easier to address while you still have contract rights.
Attend when you can
The written report is what counts, but attending at the right time lets you see how systems operate and ask practical questions.
Let the inspector work methodically. A running commentary at every step distracts from the inspection; a focused review of significant findings at the end is far more useful. Ask which items need immediate attention, which need another professional, and which are ordinary maintenance. Take notes, but rely on the final written report for findings and limitations.
Sort defects from maintenance from preferences
Not every item carries the same weight. Organize findings into five buckets:
- Safety concerns or active conditions needing prompt attention
- Major systems or components near the end of useful life
- Items that may affect insurance, financing, or normal use
- Deferred maintenance to budget for
- Cosmetic conditions and optional improvements
A long report does not mean the home is a bad purchase. Older homes simply produce more observations. The useful questions are how serious each item is, what it likely costs, how uncertain that estimate is, and whether it changes your decision.
Bring in specialists for unresolved questions
If your inspector recommends another evaluation, schedule it inside the contract period whenever possible. A roofer, electrician, plumber, HVAC contractor, engineer, pool professional, seawall specialist, mold assessor, or pest professional can answer questions outside a general inspector’s scope.
Verify permits and property records with the responsible local authority. An inspector may observe work that looks altered, but only the building department can say what its records show and what may be required.
Remember what inspection does not replace
Inspection does not substitute for title review, survey, association-document review, permit research, insurance quotes, flood-zone review, appraisal, or legal advice. Each answers a different question.
Federal flood maps can be reviewed through the FEMA Flood Map Service Center. For a condominium, association budgets, reserves, insurance, assessments, milestone inspections, and structural integrity reserve studies all require their own review.
Respond within the contract
Repairs, credits, price changes, acceptance of the property, and cancellation rights all depend on your signed contract and on negotiation. Do not assume the seller must repair every finding.
Discuss your options before you send a notice or let a deadline pass. The Consumer Financial Protection Bureau distinguishes an independent inspection from the lender’s appraisal and encourages buyers to understand the applicable contract contingency.
Common questions
How much does a home inspection cost in South Florida?
Fees vary with the size, age, and type of property, and with any additional evaluations you order. Ask for the fee and the scope together, since the cheapest quote may exclude systems you actually need reviewed. Treat it as a due-diligence cost rather than a place to economize.
Can the seller refuse to make repairs?
Often, yes — it depends entirely on what the contract provides. Some contracts allow a buyer to cancel within an inspection period rather than obligating the seller to repair. Read the provisions that apply to your transaction before the deadline, and take rights questions to a qualified Florida attorney.
Do I still need an inspection on new construction?
Many buyers choose to inspect new construction anyway. A new home has never been lived in, and an independent review can identify incomplete or defective work while builder warranty periods are still open. Confirm what your contract allows and when.